Valor | Energy Connection – September 21, 2026

September 21, 2026 Edition

At Valor, our goal is to keep you informed of the latest news and updates from the oil and gas industry. We are committed to sharing the insights and knowledge that our team gathers to help you stay ahead in this dynamic sector. From mergers and acquisitions to regulatory changes and technological advancements, we cover all the key developments that impact the industry. Stay tuned for weekly updates to keep you well-informed.


  • Enbridge launches open season for West Texas Express natural gas pipeline
    Summary: Enbridge launched a non-binding open season for its proposed 2-bcfd West Texas Express natural gas pipeline project to transport Permian basin supply west from Waha to El Paso area markets. The project is currently expected to include over 150 miles of new 42-inch OD pipeline, with potential laterals serving Hudspeth County, Texas, and delivery points at the U.S.-Mexico border. Pending commercial support and approvals, Enbridge targets a Q4 2029 in-service date, with the open season closing on September 25, 2026.
  • Read more
  • U.S. oil, gas rig count creeps up with strong prices
  • Summary: Baker Hughes reported that active U.S. drilling rigs increased to 595, reflecting a 53-rig gain from last year as oil and gas rigs both rose by two to 452 and 134, respectively. EIA data showed weekly domestic crude production averaged 13.944 million bpd, down slightly week-over-week but up 462,000 bpd from last year. Additionally, Primary Vision’s Frac Spread Count added six crews to reach 184, while Permian Basin active rigs rose by one to 269, standing 15 rigs above year-ago levels.
  • Read more
  • Oil falls as supply fears ease
  • Summary: Global crude oil prices fell for a third straight session, with Brent edging 0.9% lower to $103.87 a barrel and WTI dropping 1.6% to $100.30 per barrel. Easing supply concerns followed reports that Saudi Aramco plans to partially restart its 7-million-barrel-per-day East-West pipeline within days and achieve full capacity within six weeks. Despite the price decline, money managers increased their net-long positions across Brent and WTI by 18,254 lots to 429,413 lots through September 15.
  • Read more
  • EIA forecasts continued growth in U.S. crude oil production through 2026
  • Summary: U.S. crude oil production is projected to reach a record 13.8 million b/d in 2026, up from 13.7 million b/d in 2025, after averaging 13.7 million b/d in the first half of 2026. Permian production is forecast to average 6.8 million b/d in 2026, a 3% increase over 2025 supported by WTI prices averaging $84/bbl through August compared to $65/bbl in 2025. Federal Gulf of Mexico output rose 10% or 0.2 million b/d in first-half 2026, driven by four projects including Shenandoah at 70,000 b/d.
  • Read more
  • U.S. natural gas market verging on record growth
  • Summary: The EIA projects U.S. natural gas production to reach record highs of 111.7 bcfd in 2026 and 115.9 bcfd in 2027, up from 107.6 bcfd in 2025. Domestic consumption and average LNG exports are also set to expand, with LNG exports forecast to rise from 15.1 bcfd in 2025 to 17.4 bcfd in 2026 and 18.6 bcfd in 2027. An EY benchmark study noted that natural gas production rose 18% and reserves increased 14%, even as industry capital expenditures fell 49% and overall M&A spending dropped 70% year over year.
  • Read more
  • U.S. shale producer HighPeak Energy is exploring a sale
  • Summary: HighPeak Energy is exploring a potential sale after receiving an acquisition offer from an unnamed foreign party for its Permian Basin operations. The Fort Worth-based firm has engaged investment banks Evercore and Texas Capital Securities to solicit prospective buyers. According to LSEG data and company presentations, HighPeak had a $1 billion market capitalization with $1.1 billion in long-term debt at the end of June, and produced about 45,500 boepd across 140,000 acres in the first half of the year.
  • Read more
  • U.S. oil inventories jump as Cushing stocks keep falling
  • Summary: The American Petroleum Institute estimated that U.S. crude oil inventories increased by 7.14 million barrels for the week ending September 11, while Cushing stocks fell by 246,000 barrels. Meanwhile, SPR inventories declined by 400,000 barrels to 285 million barrels, and U.S. production for the week ending September 4 rose to 13.947 million bpd. Gasoline and distillate inventories gained 1.46 million barrels and 1.61 million barrels respectively, as Brent crude reached $108.68 and WTI hit $107.38.
  • Read more


Contact Valor Today

Contact us today if you need help outsourcing your oil and gas operations.

The information provided by Valor in this blog is for general informational purposes only, not to provide specific recommendations or legal or tax-related advice. The blog/website should not be used as a substitute for competent legal advice from a licensed professional attorney in your state.

Henry Hub vs. WTI: Which Price Actually Drives Your Royalty Check?

Open your royalty statement and you will see two numbers that matter more than almost anything else on the page: Open your royalty statement and you will see two numbers that matter more than almost anything else on the page: the price your operator paid you for oil and the price paid for gas. Both move independently, both reference national benchmarks — West Texas Intermediate (WTI) for oil and Henry Hub for gas — and neither benchmark alone dictates your total payout. Which benchmark impacts your income more depends on what your wells produce, where they sit, and how your operator markets the production.

Your Check Reflects a Product Mix, Not a Single Price

Every royalty check represents multiple underlying revenue streams combined into a single distribution:

  • Oil Value: Oil sales volume × applicable oil sales price
  • Gas Value: Gas sales volume × applicable gas sales price
  • NGL Value: Liquids volume × applicable NGL price (when separately reported)

Your total payout then reflects your net revenue interest (NRI) less applicable production taxes, adjustments, or permitted post-production deductions.

The relative size of these streams — your product mix — determines whether WTI or Henry Hub has a greater impact on your monthly check.

Basin / RegionPrimary Commodity ExposureKey Benchmark References
Permian Basin (Reagan, Midland, Martin)Heavily Oil-WeightedWTI (adjusted for WTI Midland/MEH pricing)
Haynesville (East TX, NW Louisiana)Primarily Dry GasHenry Hub
Anadarko Basin (Western Oklahoma)Dry Gas to Wet Gas / NGLsHenry Hub & Mont Belvieu
Eagle Ford & SCOOP/STACKMixed / Liquids-RichWTI & Mont Belvieu Liquids

A common surprise for mineral owners is discovering their true commodity exposure looks nothing like they assumed. A tract thought to be purely “an oil property” often yields substantial gas and NGL revenue once every line item is accounted for. For a deeper look at how interest structures shape what shows up on your statement, our Mineral Management Overview lays out the framework.

When WTI Matters Most

WTI (West Texas Intermediate) is the light, sweet crude benchmark priced at Cushing, Oklahoma. If your wells sit in the Permian, Eagle Ford, SCOOP/STACK oil window, Bakken, or DJ Basin, WTI movements strongly influence your crude oil revenue.

However, the realized price on your statement is rarely WTI flat. Realized sales prices may sit above or below WTI depending on regional basis, location, crude quality, contract terms, and sale timing. For example, WTI Midland is a regional crude price that can trade at a premium or discount to Cushing pricing rather than serving as a standard flat deduction.

Key items to audit on oil-weighted statements:

  • Realized Price per Barrel: Compare the reported unit price against monthly benchmark averages for the specific production month (not check month).
  • Itemized Deductions: Audit separate line items for gathering, transportation, or marketing costs.
  • Deduction Calculations: Verify whether discounts or fees are applied before or after net price realizations.

When Henry Hub Matters Most

Henry Hub is the standard U.S. natural gas benchmark, priced at Henry Hub in Erath, Louisiana. If your acreage sits in the Haynesville, Marcellus/Utica, or dry-gas windows of the Anadarko Basin, natural gas pricing dictates the bulk of your check.

Haynesville economics are closely tied to Henry Hub due to proximity to Gulf Coast LNG export terminals and industrial demand, though actual realized prices still vary based on delivery points and sales contracts. Elsewhere, regional differentials can create significant swings. In the Permian Basin, for instance, Waha hub gas has historically traded at deep discounts — and occasionally negative prices — when regional pipeline takeaway capacity fills up.

For NGL-rich acreage (wet gas in the Anadarko or Eagle Ford), products like propane, butane, ethane, and natural gasoline price against Mont Belvieu benchmarks. NGL revenue can help offset weaker dry-gas pricing, depending on liquids yield and realized NGL prices.

Understanding Payment Timing and Settlement Lag

A common question from mineral owners is: “WTI was up last month, so why did my check drop?” One common reason is settlement lag.

Royalty payments commonly trail the production or sales month by one to three months, depending on the commodity, operator practices, state statutory deadlines, and specific lease agreements. For example, under Texas law, ongoing royalty proceeds are generally payable up to 60 days after the sales month for oil and 90 days for gas. Oklahoma law similarly provides for payment timelines spanning two to three months following production.

  • Month 1: Physical Production & Field Delivery
  • Month 2: Operator Reconciliation, Invoicing & Purchaser Accounting
  • Month 3 (or 4): Royalty Distribution Issued to Owner

Because of this delay, September production may not appear on a royalty check until November or December. Building this lag into your expectations prevents unnecessary confusion during market swings. Valor’s team of CPAs, CPLs, and Certified Mineral Managers — view our credentials on the Valor Team Page — systematically audits payment timing and pricing accuracy to protect against delayed or miscalculated distributions.

When Benchmarks Diverge — Practical Audit Steps

A portfolio with both oil- and gas-linked revenue may be less exposed to movements in a single commodity when WTI and Henry Hub diverge. However, ensuring you receive full value requires routine statement verification:

  1. Compare Unit Prices: Match check unit prices against historical benchmark averages and regional market adjustments for that production month.
  2. Reconcile Volumes: Cross-reference statement volumes with state regulatory filings, keeping in mind that wellhead production and sales volumes may not match 1-to-1 due to allocations, processing shrinkage, lease fuel, or flaring.
  3. Audit Deductions: Flag any month where post-production deductions (gathering, compression, processing, transportation) jump as a percentage of gross revenue.
  4. Monitor Suspended Balances: Track held funds following title transfers, operator changes, or property acquisitions.

Valor has recovered more than $32 million for mineral owners in the past 36 months through royalty auditing, including underpayments, suspended balances, and deduction errors. Watch our 2-minute mineral management overview to see how audit recovery works.

Contact Valor Today

Understanding which benchmarks impact your check is the first step; verifying that your operator calculates your distributions accurately is where value is preserved. If you want a professional audit of your statements, deductions, and revenue accuracy across your assets, Valor’s expert team provides comprehensive mineral management solutions.

Contact Valor today for a review of your royalty statements and revenue performance.

Disclaimer: The information provided by Valor in this blog post is for general informational purposes only and does not constitute financial, legal, or tax advice.

Valor | Energy Connection – September 14, 2026

September 14, 2026 Edition

At Valor, our goal is to keep you informed of the latest news and updates from the oil and gas industry. We are committed to sharing the insights and knowledge that our team gathers to help you stay ahead in this dynamic sector. From mergers and acquisitions to regulatory changes and technological advancements, we cover all the key developments that impact the industry. Stay tuned for weekly updates to keep you well-informed.


  • Brent oil passes $108 per barrel
    Summary: Brent crude spiked to $108.49 per barrel and WTI reached $106.60 after Saudi Arabia closed its East-West pipeline, putting about 4% of global supply at risk. Global supply projections indicate 100.7 million bpd in 2026, down 5.7 million bpd year-over-year, as inventories dropped by 507 million barrels since February. Additionally, U.S. August headline CPI rose 3.4% year-over-year and final-demand PPI advanced 5.4%, creating an 86% market-implied probability of a 25-basis-point interest-rate increase.
  • Read more
  • Summit Petroleum reports success in Upton County with U-turn lateral wells
  • Summary: Summit Petroleum completed five U-turn lateral wells in Upton County, achieving an average initial production rate of 1,584 barrels per day in the southern Midland Basin. The company’s 10-well development plan includes seven U-turn laterals and three straight laterals, with targets in the Jo Mill, Wolfcamp B, and Spraberry formations. Operations averaged 20 days from drill to rig release versus an estimated 23 days for the 21,000-foot measured depth wells across Summit’s single section of land.
  • Read more
  • U.S. rig count rises to 591 as oil and gas drilling both increase
  • Summary: The U.S. rig count increased by three to 591 for the week ending September 11, standing 52 rigs or nearly 10% above the 539 operating a year ago. Oil rigs rose by one to 450 while natural gas rigs increased by two to 132, reflecting year-over-year gains of 34 oil rigs and 14 gas rigs. Regional activity showed the Williston Basin adding five rigs to reach 32 and North Dakota gaining four to reach 28, while New Mexico lost three rigs to drop to 92 and the Permian remained unchanged at 268 rigs.
  • Read more
  • Summit Midstream confirms expansion of Double E pipeline in Delaware Basin
  • Summary: Summit Midstream made a final investment decision to expand the Double E pipeline by installing a compressor station to increase forward haul capacity to the Waha hub by about 900 million cfd. The company signed a new long-term transportation agreement for 200 million cfd, raising total contracted capacity on Double E to roughly 2.2 billion cfd. Supported by 550 million cfd of binding commitments, the expansion project targets an in-service date in Q4 2028 with discussions ongoing for 450 million cfd.
  • Read more
  • U.S. natural gas market verging on record growth
  • Summary: The EIA projects U.S. natural gas production to reach record highs of 111.7 bcfd in 2026 and 115.9 bcfd in 2027, up from 107.6 bcfd in 2025. Domestic consumption and average LNG exports are also set to expand, with LNG exports forecast to rise from 15.1 bcfd in 2025 to 17.4 bcfd in 2026 and 18.6 bcfd in 2027. An EY benchmark study noted that natural gas production rose 18% and reserves increased 14%, even as industry capital expenditures fell 49% and overall M&A spending dropped 70% year over year.
  • Read more
  • Soaring oil prices put Fed on track for September rate hike
  • Summary: Data from CME Group indicates 90% of trading respondents expect a 25-basis-point Fed rate hike following crude’s rise above $100 per barrel, an 8% gain last week, and Brent briefly topping $108. ING analysts highlighted that the August inflation reading of 3.4% remains well above target, with monthly core consumer prices up 0.29%. Meanwhile, AAA data shows U.S. national average fuel costs reaching $4.3120 per gallon for gasoline and rising to $6.2040 for diesel after diesel touched a $6 record.
  • Read more
  • Debunking the viral claim that America has only 14 days of oil left
  • Summary: A viral claim misleads by comparing the 286.6 million barrels in the Strategic Petroleum Reserve with 20.7 million barrels per day of petroleum product demand, ignoring continuous domestic crude output of 13.9 million barrels per day and commercial stocks of 424.5 million barrels. The SPR, which held 638 million barrels in 2020, stands at its lowest level since November 1982 after a 180-million-barrel Biden release and a 172-million-barrel Trump exchange commitment. Recent DOE releases saw SPR stocks decline by 650,000 barrels daily over four weeks.
  • Read more


Contact Valor Today

Contact us today if you need help outsourcing your oil and gas operations.

The information provided by Valor in this blog is for general informational purposes only, not to provide specific recommendations or legal or tax-related advice. The blog/website should not be used as a substitute for competent legal advice from a licensed professional attorney in your state.

How to Locate a Mineral Tract From a Deed Description

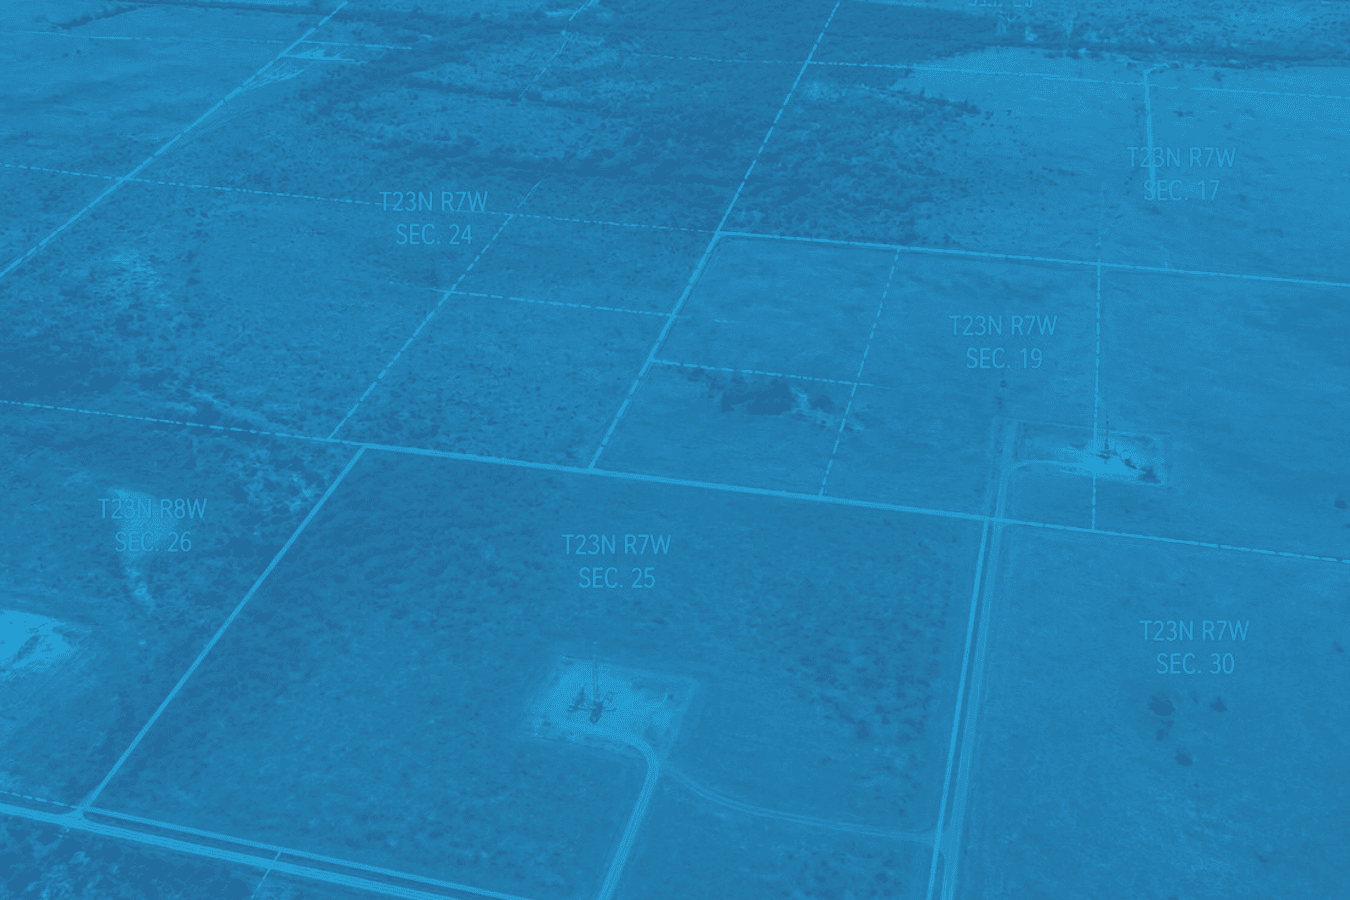
A deed that reads “320 acres, more or less, out of the H&TC RR Co. Survey, Abstract 412, Reagan County, Texas” tells you exactly where your minerals are — if you know how to read it. Most heirs do not, and that is the reason a shoebox of family paperwork often sits untouched for years while wells produce nearby.

This guide walks through the free public tools that translate a Texas or Oklahoma legal description into a shape you can see on a map, in the order you should use them. You will finish with a repeatable process and a short list of the traps that catch first-time researchers. If you have recently inherited minerals and are not sure what you own or where it is, read Just Inherited Mineral Rights? Here Is Where to Start before working through the steps here.

Read the Deed First: Survey, Abstract, and Varas

Before any map is useful you have to decode the language on the page. Texas never adopted the federal section-township-range grid used across most of the western United States. Instead, Texas land is described by original land grant surveys, each identified by a survey name — often the original grantee, a railroad, a colonist, or an empresario — and an abstract number assigned by the county. “H&TC RR Co. Survey, A-412” means the Houston and Texas Central Railroad Company survey, abstract 412, in whatever county the deed names. The abstract number is county-specific, so A-412 in Reagan County is a different tract than A-412 in Midland County.

Older Texas deeds also use varas — a Spanish colonial unit of measure — for metes-and-bounds calls. One vara equals roughly 33.33 inches, or about 2.778 feet. A call of “1,900 varas” is therefore about 5,278 feet, or just under a mile. If your deed reads “thence north 1,900 varas to a stake,” you will need that conversion before you can sketch the tract or compare it to a modern plat.

Oklahoma is simpler on this front. It uses the standard Public Land Survey System, so tracts are described by section, township, and range — for example, “NE/4 of Section 14, Township 6 North, Range 5 West.”

Write down every element from the deed before you open a browser: county, survey name, abstract number, section-township-range for Oklahoma tracts, acreage, and any adjoining landowners or physical monuments named in the description. You will use all of it. For a broader guide to researching mineral ownership at the county level, read Valor’s courthouse mineral research guide.

Step 1: Start With the RRC Public GIS Viewer

The Texas Railroad Commission’s public GIS Map Viewer is the fastest way to see wells, leases, and survey boundaries overlaid on aerial imagery. It is free, requires no login, and covers every county in the state. Search by county and abstract number, or zoom to the county and toggle the survey and abstract layers to see the grid of original grants. Once you find your abstract, turn on the wells layer to see permitted, producing, and plugged wells inside it — often the first confirmation that your family’s tract is or was under active development.

The RRC viewer is authoritative for wells and permits but only approximate for survey boundaries. Original surveys were run with chains and compasses in the 1800s, and modern GIS shapefiles are best-fit reconstructions, so expect the lines to drift from where a modern professional survey would place them. Use the viewer to locate the general area, then move to the appraisal district for a tighter picture.

For Oklahoma, the equivalent starting point is the Oklahoma Corporation Commission’s well records combined with the BLM’s General Land Office Records site, which lets you look up any section-township-range and pull the original federal patent. For a plain-language guide to reading permit and drilling activity once you have located your tract, read How to Read Oil and Gas Activity on Your Acreage.

Step 2: Cross-Check the County Appraisal District

Every Texas county has a Central Appraisal District that maintains parcel-level maps for property tax purposes. These maps are usually more current and more precise than the RRC survey layer because they are maintained for taxation, not historical reference. Search the appraisal district site by owner name or by abstract number. A hit will return a parcel record with acreage, a legal description, and a plat showing the tract outlined against neighboring parcels.

Two things to verify at this stage. First, confirm the acreage roughly matches the deed. A deed calling for 320 acres but an appraisal district parcel showing meaningfully less suggests either a partial conveyance somewhere in the chain of title or a boundary correction — either of which needs investigation before you rely on the map.

Second, confirm the owner name. If the appraisal district still lists a great-grandparent who died decades ago, the surface has likely been sold off but the minerals may still belong to the family, since Texas allows severed mineral estates to pass separately from surface. This is one of the most common patterns Valor’s mineral management team sees, and it is exactly why professional mineral work starts with a clean title review. If the interest appears to still be titled in a deceased relative’s name, read Inherited Minerals With No Paper Trail before proceeding.

Step 3: Use the Texas GLO and Oklahoma Federal Records for the Origin Story

The Texas General Land Office maintains the original patent files for every survey in the state, most of them scanned and searchable through the GLO’s Land Grant Database. Pulling the original patent gives you the field notes, the sketch the surveyor drew in the 1800s, and the name of the original grantee. This matters for resolving conflicts between adjoining surveys — which overlap more often than you would expect — and as the ultimate authority when a modern description references “the original H&TC survey line.”

For Oklahoma tracts, the BLM General Land Office Records site is the federal equivalent. Search by state, county, and section-township-range to pull the original homestead patent or railroad grant. Oklahoma’s Public Land Survey System grid is stable and well-documented, so once you have the correct section-township-range from the deed, locating the tract on a modern map is largely mechanical. The complication in Oklahoma is usually not finding the tract — it is untangling fractional mineral interests that have been divided across generations of heirs.

Common Traps: Duplicate Names, Obsolete Lots, and Re-Surveyed Abstracts

A few patterns cause more grief than any others.

Duplicate survey names. Texas has multiple “H&TC RR Co.” surveys because the railroad received grants across dozens of counties, and there are multiple surveys in the same name because common names appear throughout the historical record. The abstract number plus the county is what makes the description unique — never rely on the survey name alone.

Obsolete lot or block numbers. Many rural Texas subdivisions from the early 1900s were platted, sold, and then vacated or re-platted decades later. A deed referencing “Lot 7, Block 3, Sunset Acres” may point to a plat that no longer legally exists, in which case you need the original plat filed at the county clerk to reconstruct the boundaries.

Re-surveyed abstracts. When a county discovers a gap or overlap between adjoining original surveys, it sometimes creates a new abstract number for the corrected area. An old deed will reference the historical abstract. The appraisal district will show the modern one. Both describe the same ground at different points in history.

Obsolete physical monuments. Deeds that reference “the large post oak” or “the fence corner” are legally valid but functionally ambiguous if those features no longer exist. Resolving them usually requires a professional surveyor or an experienced landman. Valor’s team of certified professional landmen and Certified Mineral Managers works through these situations every week.

When to Stop and Call a Professional

The free tools above will take most owners a long way. Stop and bring in professional help when:

The survey name and abstract number do not appear in any of the databases above — this usually means the original grant predates the current county’s organization and the records are in an archived predecessor county.

The deed describes adjoining owners or monuments rather than a survey name and abstract, and those references are not resolvable from modern records.

The appraisal district shows meaningfully less acreage than the deed and the chain of conveyances is unclear.

You have located the tract but found a well or lease on it that does not match any division order or royalty check in your records.

In each of these cases, a CPL running a title search from the original patent forward is the right next step — not more time in the free databases. For context on what that process looks like and what it costs, read Attorney, CPA, Landman, or Mineral Manager: Who to Hire for What.

Valor has recovered more than $32 million for mineral owners across roughly 500,000 wells in 32 states, and most of that work started with someone holding a deed they could not read. If you have gone as far as you can on your own, Contact Valor and our team will take it from there.


Contact Valor Today

Locating a mineral tract is step one. Confirming the ownership is clean, finding out which wells are producing from it, and getting paid are steps two, three, and four. Contact Valor today for a free, no-obligation mineral asset review — our mineral management team of CPAs, CPLs, and Certified Mineral Managers will locate your tract, run the title, identify any wells or operators connected to it, and tell you what you actually own before you respond to any offer or sign any document. We handle mineral ownership verification for owners across Oklahoma, Texas, and 30 other states.

The information provided by Valor in this blog is for general informational purposes only and is not intended to provide specific recommendations or legal or tax-related advice. This blog should not be used as a substitute for competent legal advice from a licensed attorney in your state.
What Are Leases Going For? How to Benchmark a Lease Offer When Bonus Data Is Private

An offer letter shows up in the mail. It lists a per-acre bonus, a royalty fraction, a primary term, and a signature line. What it does not tell you is what your neighbor received last month for comparable acreage in the same formation.

That information gap is one of the biggest challenges mineral owners face when evaluating a lease offer — and one of the most consequential. Valor has recovered more than $32 million for mineral owners, and a meaningful share of that came from lease terms negotiated correctly the first time rather than fixed after the fact. This post covers why bonus data is hard to find, where real comparables live, how to evaluate a tiered offer, and which clauses matter as much as or more than the headline number.

For a plain-language breakdown of the specific lease clauses that control long-term value, read How to Negotiate an Oil and Gas Lease first.

Why Bonus Amounts Are Not in Public Records

When a lease is recorded at the county clerk’s office in Texas or Oklahoma, the document filed is typically a memorandum of lease or the lease itself. The consideration line almost always states a nominal amount rather than the actual negotiated bonus. That is deliberate — operators do not want the bonus they paid you to become the floor for the next owner across the section line.

The practical consequence is that there is no MLS for mineral leases. You cannot pull up a state database and see what an operator paid nearby owners last quarter. Landmen know the market because they are actively making offers across an area and seeing current terms in real time. Mineral owners typically have a much narrower view.

That asymmetry is structural, and it is why the first move on any offer is not to negotiate the bonus in isolation — it is to build a broader picture of the market before you respond.

Where Real Comparables Actually Live

Useful comparables exist. They require triangulation across three sources, none of which will hand you a bonus number directly.

Recorded leases at the county clerk. The bonus amount is typically not disclosed, but the royalty fraction, primary term, depth clauses, Pugh clause language, shut-in provisions, and post-production cost language are all there. If recently recorded leases in your section consistently show a stronger royalty position or shorter primary term than the offer in front of you, that is a meaningful signal worth acting on. For a guide to pulling county records yourself, read Valor’s courthouse mineral research guide.

OCC pooling orders in Oklahoma. When an operator force-pools a section under the Oklahoma Corporation Commission, the resulting order documents the bonus and royalty alternatives established through the pooling process. These are public. Pulling recent pooling orders in your township and range gives you a defensible bonus-and-royalty reference point for that specific formation — the closest thing to a published price sheet that exists in either state. For context on how force pooling works and what it means for unleased owners, read Forced Pooling in Oklahoma vs. Texas.

RRC filings in Texas. Railroad Commission permit and completion filings show who is drilling, where activity is concentrated, and how development is progressing near your tract. If an operator has filed several horizontal permits within a mile of your acreage in recent months, the offer in your hand is part of an active leasing campaign — and the bonus is negotiable. Permit density is a leverage indicator, not a price indicator, but it tells you which side of the table has urgency. For a plain-language guide to reading permit and drilling activity near your acreage, read How to Read Oil and Gas Activity on Your Acreage.

Building this picture takes time and a working knowledge of what to look for. It is the work Valor’s mineral management team does before any client responds to an offer.

How to Think About a Tiered Offer

Operators frequently present three options on a single offer letter. The structure is almost always the same: a higher bonus paired with a lower royalty, a middle option, and a lower bonus paired with a higher royalty. The bonus is guaranteed cash at signing. Royalty is a percentage of production revenue that only pays if and when a well is drilled and produces.

A real-world example from an active Anadarko Basin leasing campaign this week: a landman presented three options at one thousand dollars per acre at three-sixteenths royalty, eight hundred dollars per acre at one-fifth royalty, and one hundred dollars per acre at one-fourth royalty. The instinct is to circle the highest bonus. That can be a mistake if the long-term royalty economics are ignored.

The real question is: how much production, over what timeframe, does it take for the higher-royalty option to overtake the higher-bonus option? The answer depends on unit size, your net acre position inside that unit, expected production, commodity prices, and timing. There is no universal break-even, but the math is workable using realistic production assumptions for the area.

If drilling is relatively likely based on nearby permit activity, the higher-royalty option will often create substantially more long-term value than the larger upfront bonus. If the acreage is speculative with limited nearby development, the guaranteed upfront consideration may weigh more heavily in the decision. You cannot make that call by looking at the bonus number alone. For help converting your net mineral acres to net royalty acres so you can run the economics accurately, read Net Mineral Acres vs. Net Royalty Acres: How to Read an Offer Correctly.

Clauses That Move More Money Than the Bonus

The bonus is the number that gets circled on the offer letter. It is rarely the number that determines what the lease is worth over its life. Four clauses deserve equal or greater attention.

Option to extend. A primary term with an option to extend at the same bonus per acre gives the lessee additional time to develop under terms negotiated at the outset. Owners should either strike the option, price it at a meaningful premium, or shorten the primary term in exchange for removing it.

Paid-up versus delay rental. A paid-up lease provides the agreed consideration at signing and requires no annual payments to maintain the lease during the primary term. A delay-rental lease requires periodic payments to keep the lease in force. Paid-up structures are more common today, but confirm which structure is being offered before comparing headline bonus numbers across competing offers.

Cost-free royalty language. Post-production costs — gathering, compression, treating, transportation, and marketing — can materially reduce royalty economics depending on lease language and applicable law. On gas-weighted wells, significant deductions can mean a higher royalty subject to full costs pays less than a lower cost-free royalty. For a full explanation of how sales-point language produces legal deductions even under a clause that says no deductions, read Cost-Free Royalty Clauses: Why You Still See Deductions on Your Check.

Pugh clause and depth severance. Without appropriate acreage and depth-release provisions, production from a limited portion of the leased premises can hold substantially more acreage or depth than the owner expected at signing. These are the terms Valor’s lease negotiation team reviews on every client offer before a response is made.

What a Real Benchmarking Process Looks Like

Valor manages roughly 500,000 wells across 32 states and 13 major basins. When an offer lands on a client’s tract in the Permian, the SCOOP/STACK, or the Haynesville, we are often already seeing recent lease activity, permit pace, and pooling terms in that area. That visibility provides the context the operator is already working from.

A defensible benchmarking process reviews recently recorded leases in the section and adjoining sections, recent OCC pooling orders for Oklahoma tracts, RRC permit and completion activity for Texas tracts, the economics of any tiered offer against realistic production assumptions, and the lease form itself for cost-free royalty language, Pugh clauses, extension options, and shut-in provisions. Done properly, it usually changes the outcome.

An offer letter is a starting position, not a final price. If you are holding one now and have no way to benchmark it, Contact Valor — our mineral management team can pull the comparables and review the lease before you sign. For owners who want to evaluate whether they should lease at all before responding, read Before You Sell or Lease.


Contact Valor Today

An offer letter is a starting position. Understanding the surrounding market, development activity, royalty structure, and lease language before responding can materially affect the outcome. Contact Valor today for a free, no-obligation review — our lease negotiation team will pull available comparables, evaluate tiered offer economics, and mark up the lease form for cost-free royalty language, Pugh clauses, and extension options before you sign anything. We handle lease offers and lease negotiations for mineral owners across Oklahoma, Texas, and 30 other states.

The information provided by Valor in this blog is for general informational purposes only and is not intended to provide specific recommendations or legal or tax-related advice. This blog should not be used as a substitute for competent legal advice from a licensed attorney in your state.
Royalties in Suspense: The Letter That Starts the Clock

Valor has recovered more than $32 million in royalty proceeds for mineral owners — and a meaningful share of that money was sitting in suspense at an operator, waiting on a letter that never got written. If your royalty payments have stopped, slowed, or never started on a well you know is producing, there is a real chance your interest is in suspense. This post explains what suspense actually means, why operators hold funds, how to kick off the certified-letter process, and why getting all the way to a full recovery usually requires more than a single letter.

What suspense actually means

Suspense is an accounting status, not a penalty. When an operator cannot pay a mineral owner with confidence, they park the money in a suspense account and continue accruing your share of proceeds month over month. The funds are still yours. The operator is holding them because paying the wrong party — or paying the right party at the wrong address, or paying without a valid W-9 — creates a larger problem than not paying at all.

Common reasons an interest lands in suspense: an unrecorded death in the chain of title, a divorce decree that never made it to the county clerk, a missing or expired W-9, a bad mailing address after uncashed checks are returned, a title dispute between heirs, unrecorded assignments, or a division order the owner never signed and returned. On newly drilled wells, suspense often reflects title curative that is still open — the operator’s landman flagged a gap and revenue accounting will not release funds until it clears.

Suspense is usually resolvable. It is almost never resolved automatically. Across the more than 500,000 wells in Valor’s managed portfolio, the pattern is consistent: the interests that get paid fastest belong to owners who put their request in writing and follow up. If you believe funds may already be sitting in suspense or have escheated to the state, start with Valor’s unclaimed mineral funds guide before you draft the letter.

Why the certified letter matters more than the phone call

Both Texas and Oklahoma have statutory frameworks governing how quickly operators must pay royalties after first production, and both provide for statutory interest on late-paid proceeds. The specifics — timing windows, interest rates, and notice requirements — vary by state and by the reason for the delay. Any owner planning to pursue a formal claim should confirm current statutory language with qualified counsel.

Here is the part that catches owners off guard: those remedies generally require the owner to make a written demand. A phone call to owner relations does not create a record you can later prove. A certified letter does. The certified mail receipt, the return receipt card, and a dated copy of your letter are the paper trail that establishes when the operator was formally notified, what you asked for, and how long they have taken to respond.

The certified letter also forces the file onto someone’s desk. Verbal inquiries get logged. Written demands with tracking numbers get escalated to revenue accounting, land, and sometimes legal. That escalation is exactly what you want — and it is a step most owners can take on their own. What comes after the letter is where things get more complicated.

What to put in the letter — and where the checklist gets hard

A good demand letter is short, specific, and unambiguous. Vague letters get vague responses. Include at minimum:

Your identifying information. Full legal name, current mailing address, phone number, email, and Social Security number or EIN — or a statement that a current W-9 is enclosed.

The operator’s information. Operator name and your owner or interest number if you have one from a prior check stub or division order.

The well and property information. Well name, API number, county and state, lease name, and if you know them, the section, township, and range or the abstract and survey.

Your interest. The nature of your interest — royalty, overriding royalty, non-participating royalty, or working interest — and your decimal if known. If you are not sure what your decimal should be, Valor’s royalty decimal calculator is a useful starting point.

A clear written demand. A statement that you are the rightful owner, that you believe proceeds are being held in suspense, and that you are making a formal written demand for release of all suspended funds and for regular payment going forward.

Supporting documents. A copy of the deed, probate order, divorce decree, assignment, or other instrument that establishes your ownership. A signed W-9. A signed division order if one was previously sent to you.

A request for documentation. Ask the operator to identify in writing any specific title or documentation defect they believe is preventing payment so you can cure it.

If any of those items are missing — a decimal you cannot verify, a deed you cannot locate, a probate you never completed, or a title gap you cannot explain — that is exactly where professional help makes the difference between a letter that produces results and one that gets filed away. Valor’s mineral management team runs this diagnostic every day. The letter is the starting gun. Everything behind it is the race.

Send the letter certified mail, return receipt requested, to the operator’s designated address for payment inquiries — usually printed on the back of a check stub or on the division order. If you cannot find that address, use the address on file with the Texas Railroad Commission or the Oklahoma Corporation Commission. Keep the green return receipt card when it comes back. Scan the whole packet before mailing.

Suspended funds vs. underpayment claims — do not confuse them

Suspended funds are proceeds the operator has calculated, accrued, and is holding for you. They generally do not expire on their own. Once title, address, and W-9 issues are cleared, those funds get released — often in a single catch-up check covering many months or years.

Underpayment claims are different. An underpayment is money the operator paid, but paid incorrectly — wrong decimal, wrong price, improper deductions, missed volumes, or paid to the wrong party. These claims are subject to state statutes of limitation that vary by state and theory of recovery. Every month you wait, the oldest month of a potential underpayment claim rolls closer to the edge of what may be recoverable.

If your certified letter produces a runs history, review it against production reported to the Texas Railroad Commission or Oklahoma Corporation Commission for the same well and months. Compare volumes, prices, and your decimal. Discrepancies that show a consistent pattern are what underpayment claims are built on — and building one correctly requires someone who knows what to compare and how to document it before the limitations window closes. For context on how to read your check stub against public production data, read Why Your Royalty Check Suddenly Stopped and Why Is My Royalty Check So Small?

The $32 million Valor has recovered includes both workstreams: suspended funds released by written demand, and underpayment claims documented against public production records before the limitations period closed. The first step on both is the same. Getting all the way to recovery on either one is not.

What to do if the operator does not respond

Operators are expected to respond to written demands. Many do, promptly. Some do not — because the file is genuinely complicated, because owner relations is understaffed, or because the operator has changed hands and records are in transition. If 30 days pass with no substantive response, escalate in this order:

Send a second certified letter referencing the first, attaching the return receipt, and noting that statutory interest may be accruing.

Contact the operator’s designated agent for service of process, listed with the Texas Railroad Commission or the Oklahoma Corporation Commission. This puts the letter in front of a corporate officer, not a queue.

File a complaint with the Texas Railroad Commission or the Oklahoma Corporation Commission. These agencies do not adjudicate private royalty disputes, but complaints get logged and operators notice.

Engage qualified counsel. Texas and Oklahoma both have provisions that may allow recovery of attorneys’ fees on certain payment claims after proper written notice — one more reason the certified letter matters from the beginning.

If the operator is in bankruptcy, file a proof of claim to preserve your position.

This escalation sequence is something most owners can start. But navigating it fully — knowing which escalation step fits which operator response, building the documentation package for a formal claim, and pursuing underpayment recovery before the statutory window closes — is where most owners reach the limit of what they can do alone. Valor’s mineral management team handles this work daily across 32 states and 13 basins. The certified letter gets you on the record. Getting paid is a different job.


Contact Valor Today

Sending the certified letter is a step you can take today. Getting the operator to release everything owed — suspended funds, back royalties, and statutory interest — is where Valor comes in. Contact Valor for a free, no-obligation review — our mineral management team of CPAs, CPLs, and Certified Mineral Managers will identify what is holding your funds, build the documentation package that operators and state regulators respond to, and pursue recovery through every available channel. We handle royalty management and suspense releases for owners across Oklahoma, Texas, and 30 other states.

The information provided by Valor in this blog is for general informational purposes only and is not intended to provide specific recommendations or legal or tax-related advice. This blog should not be used as a substitute for competent legal advice from a licensed attorney in your state.
Valor | Energy Connection – August 31, 2026

August 31, 2026 Edition

At Valor, our goal is to keep you informed of the latest news and updates from the oil and gas industry. We are committed to sharing the insights and knowledge that our team gathers to help you stay ahead in this dynamic sector. From mergers and acquisitions to regulatory changes and technological advancements, we cover all the key developments that impact the industry. Stay tuned for weekly updates to keep you well-informed.


  • Venezuelan oil to refill U.S. Strategic Petroleum Reserve
    Summary: The United States will use Venezuelan crude to replenish the Strategic Petroleum Reserve, which stood at approximately 290 million barrels as of August 21 — near a 44-year low and approaching the operational minimum of 250-300 million barrels. Venezuela exported 1.16 million barrels per day last month, with exports to the United States averaging 786,000 barrels daily in July, the highest level since early 2019. Port capacity constraints, including tanker wait times of up to 30 days and ongoing power outages, may slow the pace of replenishment.
  • Read more
  • Rig counts in Permian Basin, Texas increase for fourth straight week
  • Summary: Baker Hughes reported that the Permian Basin added 2 rigs to reach 267 — its highest level since June 2025 — while Texas added 4 rigs to reach 281, the most since March 2025. The U.S. total held at 588 rigs, down 5 on the week but up 50 rigs or 9.3% year-over-year, with New Mexico declining by 3 to 96. Texas posted its largest single-week gain among major producing states, reinforcing sustained basin-level confidence despite broader market volatility.
  • Read more
  • U.S. natgas falls on mild weather outlook, healthy storage
  • Summary: U.S. natural gas futures declined as milder-than-expected weather forecasts reduced near-term cooling demand and storage levels remained healthy heading into the fall shoulder season. Lower LNG feedgas flows and robust domestic production have kept supply well-supplied, limiting any meaningful price recovery despite strong international gas prices. The combination of ample storage and softening seasonal demand is expected to keep Henry Hub prices range-bound through early fall.
  • Read more
  • U.S. refiners face historic stress test as global crisis looms
  • Summary: U.S. natural gas futures declined as milder-than-expected weather forecasts reduced near-term cooling demand and storage levels remained healthy heading into the fall shoulder season. Lower LNG feedgas flows and robust domestic production have kept supply well-supplied, limiting any meaningful price recovery despite strong international gas prices. The combination of ample storage and softening seasonal demand is expected to keep Henry Hub prices range-bound through early fall.
  • Read more
  • EIA raises U.S. crude oil production forecast for 2026 and 2027
  • Summary: The U.S. Energy Information Administration raised its domestic crude oil production forecast for both 2026 and 2027, citing stronger-than-expected output from key producing basins including the Permian. The updated projections signal continued production growth even amid broader market uncertainty, providing a more constructive outlook for mineral owners tracking royalty revenue expectations. The EIA’s revised numbers reflect improved well productivity and sustained operator activity across major U.S. shale plays.
  • Read more
  • Goldman Sachs sees diesel refining margins soaring to $63 a barrel
  • Summary: Goldman Sachs revised its refining profit forecast upward, doubling its earlier projection as global diesel markets tightened sharply amid the ongoing fuel shortage. Refiners are positioned to capture margins of approximately $63 per barrel on diesel — significantly above historical norms — as supply disruptions and elevated demand continue to squeeze product inventories. The revised forecast underscores the widening gap between crude oil prices and refined fuel prices that has defined energy markets this summer.
  • Read more
  • BLM sets October oil and gas lease sale for Montana and Dakotas
  • Summary: The Bureau of Land Management announced an October federal oil and gas lease sale covering acreage in Montana and the Dakotas, providing operators and investors with access to new federally managed acreage in established producing regions. The sale represents continued federal support for domestic energy development as the U.S. works to expand production capacity amid ongoing global supply constraints. Mineral owners and operators in the region will have the opportunity to participate in competitive bidding for new drilling rights.
  • Read more


Contact Valor Today

Contact us today if you need help outsourcing your oil and gas operations.

The information provided by Valor in this blog is for general informational purposes only, not to provide specific recommendations or legal or tax-related advice. The blog/website should not be used as a substitute for competent legal advice from a licensed professional attorney in your state.

Valor | Energy Connection – August 24, 2026

August 24, 2026 Edition

At Valor, our goal is to keep you informed of the latest news and updates from the oil and gas industry. We are committed to sharing the insights and knowledge that our team gathers to help you stay ahead in this dynamic sector. From mergers and acquisitions to regulatory changes and technological advancements, we cover all the key developments that impact the industry. Stay tuned for weekly updates to keep you well-informed.


  • Continental resources significantly expands Permian Basin position with acquisition of FireBird Energy II
  • Summary: Continental Resources agreed to acquire FireBird Energy II, adding about 54,000 net acres in the Midland Basin and expanding its Permian acreage by over 40% in 14 months. The acquired assets encompass 147,000 net resource acres across more than six stacked-pay reservoirs with 307 gross operated locations. Current production from the 95% operated assets is approximately 32,000 boepd (69% oil), and the deal is scheduled to close in September 2026 subject to customary conditions.
  • Read more

    Devon Energy reaches final investment decision on Solitude Pipeline System
  • Summary: Devon Energy reached a positive Final Investment Decision on the WhiteWater-led Solitude Pipeline System, taking a 25% equity interest alongside WhiteWater (50%), MPLX (10%), Diamondback Energy (7.5%), and Western Midstream Partners (7.5%). The system features two 48-inch natural gas pipelines with a phase-one capacity of 2.25 Bcf per day targeted for mid-2029, followed by a second phase in 2030. Devon has also secured LNG-linked pricing for 100 MMcf per day in 2027 and 150 MMcf per day in 2028.
  • Read more
  • U.S. energy firms cut rigs for first time in four weeks, says Baker Hughes
  • Summary: Baker Hughes reported that U.S. energy firms reduced the total oil and gas rig count by five to 588 for the week ending August 21, marking the first decline in four weeks. Oil rigs fell by three to 452, gas rigs dropped by one to 127, and miscellaneous rigs decreased by one to nine, though the total count remains up 50 rigs or 9.3% year-over-year. Texas added four rigs to reach 281, while regional counts rose by two to 267 in the Permian basin and by one to 50 in the Eagle Ford shale.
  • Read more
  • U.S. shale majors cut spending despite higher oil prices
  • Summary: U.S. shale companies are trimming spending to reduce debt and boost shareholder returns, with Chevron and ConocoPhillips cutting spending by 10% in the first half of the year. The spending cuts come as the International Energy Agency projects a global oil deficit of 1.8 million barrels daily. Meanwhile, EIA data shows U.S. crude production reached 13.714 million barrels daily in May, with full-year average daily production expected to rise by a modest 200,000 barrels per day to 13.8 million.
  • Read more
  • EIA shows crude oil inventories still rising
  • Summary: U.S. crude oil inventories increased by 4.4 million barrels to reach 428.8 million barrels during the week ending August 14, placing commercial stockpiles right at the five-year average. Gasoline inventories rose by 700,000 barrels as daily production grew to 9.7 million barrels, while middle distillate stocks dropped by 1.5 million barrels to sit 13% below the five-year average. Over the last four weeks, total product demand averaged 20.5 million barrels per day, down 2.9% year-over-year.
  • Read more

    Enverus unveils top U.S. drillers of 2026
  • Summary: Helmerich & Payne led U.S. land drilling contractors in 1Q26 with 15.85 million feet of total drilled measured depth across 776 wells, followed by Patterson-UTI with 9.51 million feet across 442 wells. Exxon led drilling customers with 5.44 million feet drilled across 229 wells, while EOG moved up two spots to second with 3.39 million feet, ahead of Devon’s 3.30 million feet. U.S. active rigs averaged 637.6 for the week ending July 31, 2026, marking a 13% increase year over year.
  • Read more

    Exxon eyes Shell’s $8 billion U.S. chemicals business
  • Summary: Exxon is competing with LyondellBasell, Apollo Global Management, and Kuwait Petroleum Corporation to acquire Shell’s U.S. chemicals business, which could fetch $8 billion. Shell’s U.S. chemicals division comprises four production facilities across Louisiana, Texas, and Pennsylvania. Recent Shell divestments include selling a European renewable power business with 500 megawatts of capacity to TotalEnergies and a 35% stake in Cyprus Offshore Block 12 to MOL for $720 million.
  • Read more


Contact Valor Today

Contact us today if you need help outsourcing your oil and gas operations.

The information provided by Valor in this blog is for general informational purposes only, not to provide specific recommendations or legal or tax-related advice. The blog/website should not be used as a substitute for competent legal advice from a licensed professional attorney in your state.

Cost-Free Royalty Clauses: Why You Still See Deductions on Your Check

In the past 36 months, Valor has recovered more than $32 million for mineral owners — and a meaningful share of that came from a single misunderstood contractual mechanic: where the operator legally sets the point of sale for royalty calculation. If your lease has a cost-free, no-deductions, or no-expenses royalty clause and you are still seeing deductions on your check stub, you are not necessarily being cheated. In most cases you are being paid according to a lease definition you may not have negotiated tightly enough.

This post explains the sale-point relocation mechanism, why it produces legal deductions under an ostensibly cost-free clause, and what mineral owners in Texas, Oklahoma, and across the other states Valor works in should do about it. For the foundational explanation of what post-production deductions are and how at-the-wellhead versus gross proceeds language controls them, read Why Is My Royalty Check So Small? Post-Production Deductions, Explained first.

What a cost-free royalty clause actually protects

A cost-free royalty clause — sometimes titled “no deductions,” “no post-production costs,” or “gross proceeds” — says the operator cannot deduct costs from your royalty before it is calculated. On its face it sounds absolute. In practice it protects royalty only up to a specific point in the production stream. That point is called the point of sale, and it is defined either explicitly in the lease or implicitly by the operator’s marketing arrangement.

Here is the mechanic that trips up most mineral owners. Royalty is calculated as a percentage of the value of production at the point of sale. A cost-free clause says the operator absorbs the costs required to make the product marketable and get it to the sale point. It does not say the operator absorbs costs incurred after the sale point. Those downstream costs — gathering fees paid to a midstream pipeline, compression at a booster station, processing at a gas plant, transportation to a downstream index hub — are typically netted out of the sales price, which lowers the number your royalty percentage is applied against.

This is why two owners with identical “cost-free” language can receive materially different net royalties from the same well. The difference is not the clause. The difference is where the operator drew the sale-point line. Valor’s mineral management team sees this pattern across the 500,000 wells we monitor: identical-looking lease language, radically different net proceeds.

How operators legally relocate the sale point

Operators have three common ways to set the sale point at or near the wellhead — each defensible under most lease forms and applicable case law in producing states.

Wellhead sale to an affiliate marketer. The producer sells the raw stream to a marketing subsidiary at the wellhead for an index-minus price. The index-minus deduction reflects everything the affiliate will spend downstream. That deduction is baked into the sales price, not itemized on the check stub. Your royalty is calculated on the depressed wellhead price.

Sale at the tailgate of a gathering system. The gathering fee is treated as a pre-sale cost the operator absorbs, but processing, treating, and transportation are treated as post-sale. Whether these are pre-sale or post-sale is a factual determination courts have gone both ways on. Texas courts generally hold that post-production costs are deductible unless the lease expressly prohibits them. Oklahoma’s implied covenant to market has historically been interpreted more favorably toward owners, but the specific lease language still controls in both states.

Btu-adjusted sale after processing. The operator sells residue gas and NGLs separately after processing, then allocates costs back against each stream. The check stub shows deductions labeled PROC, T&F, or FUEL — and under many lease forms these are legally supportable even where the lease says “no deductions,” because the sale of the processed products is defined as a separate downstream sale.

None of this is fraud. It is contract mechanics playing out as the lease was drafted. Which is precisely why the fix is contractual, not adversarial.

Reading your check stub for sale-point clues

The line items on your check stub are the fingerprints of the operator’s sale-point definition. A few patterns to watch for:

GPT / GATH — gathering and transport. If your lease says cost-free and you still see this, the sale point sits downstream of the gathering system.

COMP — compression. Deductibility depends on whether it is required to make the gas marketable, which is typically pre-sale, or to reach a better market, which is typically post-sale.

DEHY / TREAT — dehydration and treating. Usually required to make gas marketable and often absorbed under a strong cost-free clause, but not always.

PROC / P&F — processing and fractionation. Under a wellhead-sale definition, generally deductible.

T&F / TRANS — transportation and fuel to the market hub. Almost universally treated as post-sale.

A useful diagnostic: total your monthly deductions and divide by gross value. If the ratio consistently exceeds 20% on gas royalty, the sale point is set well upstream of the market and the cost-free clause is doing far less work than the language implies. Two patterns Valor has seen recently: a 28% purchaser-paid deduction on a 25% no-expenses lease, and a 40%+ gathering charge on Oklahoma horizontal wells. Both are within ranges that warrant a lease-language review. For a full guide to reading every line on your check stub, read How to Read Your Royalty Check Stub Line by Line.

What language actually moves the sale point downstream

If you have leverage at lease negotiation or renewal, the clause language matters more than the clause title. “No deductions” alone is insufficient. Strong protective language does three things at once.

Define the point of sale explicitly. Not at the wellhead, but at the tailgate of the processing plant, at a named interstate pipeline delivery point, or at a specific published index hub such as Henry Hub or Waha. If the lease says royalty is calculated on proceeds at the index price, downstream costs cannot be netted out because the index price already reflects them. This is the single most important variable in the entire clause. For a full breakdown of cost-free royalty language and how to negotiate it before you sign, read How to Negotiate an Oil and Gas Lease.

Enumerate the specific costs the operator cannot deduct. A well-drafted clause lists gathering, compression, dehydration, treating, processing, fractionation, transportation, marketing, and fuel — by name. Enumeration prevents an operator from arguing a specific cost falls outside a general “no deductions” phrase.

Address affiliate sales directly. Require that any sale to an affiliate be at arm’s length or at the price the affiliate ultimately receives from an unaffiliated third party. This closes the wellhead-sale-to-marketing-subsidiary loophole.

For owners who cannot renegotiate an existing lease, the leverage points shift to lease expiration, Pugh clause enforcement, ratification requests on new units, and where the facts support it, challenges based on the operator’s duty to market. Those challenges require careful legal analysis and a clean production and revenue record, which is why the record-keeping matters as much as the clause itself.

Three questions to send the operator in writing

If you suspect sale-point relocation is producing improper deductions, send these three questions to owner relations by certified mail before escalating:

What is the defined point of sale under my lease, and where in the production stream does it sit? Request the operator’s written interpretation of the royalty clause and the marketing arrangement documentation.

What is included in each deduction line on my check stub, and is each cost incurred before or after the defined point of sale? Request a cost-by-cost breakdown with the contract or tariff that governs each charge.

For any sale to an affiliate, what price did the affiliate ultimately receive from an unaffiliated third party? This targets the wellhead-sale-to-marketing-subsidiary structure directly.

The responses — or the refusal to respond — will tell you whether a line-by-line reconciliation is warranted. Persistent refusal to provide cost documentation is itself a red flag and in most states the owner has a statutory right to request detailed accounting. Valor’s royalty management team handles these reconciliations as part of standard portfolio oversight.


Contact Valor Today

If your check stubs show deductions your lease appears to prohibit, the answer is rarely a phone call to the operator. It is a line-by-line reconciliation of lease language, sale-point mechanics, and reported proceeds. Contact Valor today for a free, no-obligation review — our royalty management team will pull your lease, map the sale point against your check stub deductions, and tell you whether the math lines up with what your lease actually requires. We handle royalty audits and lease-language reviews for owners across Oklahoma, Texas, and 30 other states.

The information provided by Valor in this blog is for general informational purposes only and is not intended to provide specific recommendations or legal or tax-related advice. This blog should not be used as a substitute for competent legal advice from a licensed attorney in your state.
Net Mineral Acres vs. Net Royalty Acres: How to Read an Offer Correctly

In the past 36 months, Valor has recovered more than $32 million for mineral owners — and a meaningful share of that came from owners who signed leases or accepted offers priced against a unit they did not fully understand. The single most common source of confusion is the difference between net mineral acres and net royalty acres. They sound like the same thing. They are not.

One measures the dirt you own. The other measures the income stream that dirt produces, normalized so buyers can compare a tract in Reeves County against a tract in Grady County on the same yardstick. If you have an offer letter in front of you quoting a price per NRA, this post will show you how to translate it back to what you actually own — and what to check before you sign anything.

What net mineral acres actually measure

Net mineral acres is the plainest number in the mineral world. If you own 100% of the minerals under a 40-acre tract, you own 40 net mineral acres. If you own an undivided 25% interest under that same 40-acre tract, you own 10 net mineral acres. The formula is gross acres multiplied by your undivided mineral interest.

NMA does not care about your lease. It does not care whether you are leased at 1/8, 3/16, 1/5, or 1/4. It does not care whether the tract is producing, held by production, or completely unleased. It is a static measurement of the physical mineral estate you own — the same number today as it will be in ten years, unless you buy, sell, or inherit into a different position.

That stability is why NMA is the right unit for title work, probate, tax rendition, and estate planning. It is also why NMA on its own is a poor unit for pricing an offer. Two owners with identical 10 NMA positions can have wildly different economic value depending on how their minerals are leased. If you have not yet confirmed your NMA from county deed records, Valor’s courthouse mineral research guide walks through how to do that by state.

What net royalty acres actually measure

Net royalty acres is a normalized unit. It exists because buyers need one number that lets them compare a tract leased at a 1/8 royalty in a legacy East Texas field to a tract leased at 1/4 in the Midland Basin without doing algebra on every deal. The industry standard benchmark is a 1/8 royalty — the historical default going back a century.

The formula is: NRA = NMA × (royalty rate ÷ 1/8) or equivalently NRA = NMA × royalty rate × 8.

Work through the four examples that matter most:

10 NMA leased at 1/4 royalty: 10 × (0.25 ÷ 0.125) = 10 × 2 = 20 NRA
10 NMA leased at 1/8 royalty: 10 × (0.125 ÷ 0.125) = 10 × 1 = 10 NRA
10 NMA leased at 3/16 royalty: 10 × (0.1875 ÷ 0.125) = 10 × 1.5 = 15 NRA
10 NMA leased at 1/5 royalty: 10 × (0.20 ÷ 0.125) = 10 × 1.6 = 16 NRA

Same 10 acres of dirt in every case. The revenue interest under each barrel produced, however, ranges from 10 to 20 NRA. A buyer paying $10,000 per NRA would offer $100,000 for the 1/8 position and $200,000 for the 1/4 position — and both offers would be internally consistent from the buyer’s point of view.

This is also why royalty rate matters so much at the lease stage. The royalty fraction you negotiate today determines your NRA count for the life of every well drilled under that lease. For a full breakdown of why royalty rate beats bonus in the long run, read How to Negotiate an Oil and Gas Lease.

Why offer letters quote price per NRA — and why that matters to you

Almost every serious mineral buyer — private capital, royalty aggregators, publicly traded royalty trusts — underwrites in dollars per NRA. They do this because NRA is directly proportional to the barrel and MCF revenue stream a buyer will collect. A tract’s NRA count multiplied by projected production per acre and commodity price gives them a discounted cash flow input. NMA does not.

The practical consequence for a mineral owner: if you receive an offer that says “$8,500 per net royalty acre,” you cannot evaluate it until you know your NRA count — which means you need both your NMA and your royalty rate. If your family records show 40 NMA and your lease is at a 3/16 royalty, that is 60 NRA and the offer is $510,000, not $340,000.

This is where owners get hurt. If an owner sees “$8,500 per acre” and mentally applies it to their 40 NMA, they anchor to $340,000 and may accept an offer well below what the buyer was actually prepared to pay for their 60 NRA position. For context on what buyers already know about your tract before they send that letter, read You Just Got an Offer for Your Minerals. Here’s What the Buyer Already Knows.

The reverse problem also occurs. An owner with a 1/8 lease who assumes the buyer’s per-NRA quote applies to NMA overestimates the offer and pushes back on a fair number. Either way the mismatch between the unit the buyer is using and the unit the owner is thinking in creates avoidable friction and money left on the table. Valor’s mineral management team reviews offer letters routinely and translates them into both units before a client responds. If you have received an offer and want to understand whether the letter is a division order, lease offer, or purchase offer before doing the math, read Division Order, Lease Offer, or Buyout? How to Read the Letter About Your Mineral Rights.

Lease offers use the same math — with higher stakes

The NMA versus NRA distinction is not limited to purchase offers. It runs through lease bonus negotiations too, but with a twist: the royalty rate is the thing being negotiated, so the NRA figure is a moving target during the discussion.

Consider 20 NMA in a Reagan County section. A landman offers $2,000 per acre bonus at a 3/16 royalty. That is $40,000 in bonus for 30 NRA of long-term revenue exposure. A competing landman offers $1,500 per acre bonus at a 1/4 royalty. That is $30,000 in bonus for 40 NRA. The bonus is lower but the NRA count is 33% higher — and over a typical horizontal well’s producing life, the incremental royalty stream can dwarf the bonus differential many times over.

Owners who evaluate lease offers only on the front-end bonus per NMA systematically undervalue the royalty rate. This is one of the most expensive mistakes in the entire mineral owner playbook and it compounds every year the well produces. Across the 500,000 wells Valor manages, the pattern is consistent: royalty rate drives lifetime revenue far more than bonus does.

A simple checklist before you sign anything

Before you respond to a purchase offer or a lease proposal, work through these five items:

Confirm your NMA from title. Do not rely on family memory or an old division order. Pull the deeds and calculate gross acres multiplied by your undivided interest. If title is unclear or the paper trail is broken, read Inherited Minerals With No Paper Trail before you respond to anything.

Confirm the royalty rate on record. For a purchase offer this is the royalty in your existing lease. For a lease offer this is what is on the table. If you are not sure what your current royalty rate is, Valor’s royalty decimal calculator can help you work backward from your check stub.

Convert to NRA using NMA × royalty rate × 8. Write both numbers down side by side before you read the offer price.

Ask the counterparty which unit their price applies to — in writing. “/acre“isambiguous.“/acre” is ambiguous. “/acre”isambiguous.”/NRA” or “$/NMA” is not. The distinction can be worth tens of thousands of dollars on a modest interest.

Compare against recent arm’s-length transactions in the same county and formation. A fair $/NRA in the Midland Basin is not a fair $/NRA in the SCOOP and neither is a fair $/NRA in the Haynesville. Valor manages minerals across 32 states and 13 major basins and can benchmark any offer against what comparable acreage is actually trading for. Start at Before You Sell or Lease for the full framework.


Contact Valor Today

Getting NMA and NRA right is the difference between negotiating from your buyer’s spreadsheet and negotiating from your own. Contact Valor today for a free, no-obligation review — our mineral management team will translate your offer into both units, benchmark it against comparable transactions in your county and formation, and tell you whether the number on the table lines up with what your minerals are actually worth. We review lease offers and purchase offers for owners across Oklahoma, Texas, and 30 other states.

The information provided by Valor in this blog is for general informational purposes only and is not intended to provide specific recommendations or legal or tax-related advice. This blog should not be used as a substitute for competent legal advice from a licensed attorney in your state.